UPI was once an unused payment method, and credit cards were still in use. Now they are not. In 2026, even more Indians will be using credit cards to pay at the counter of shops, and will be linking them to UPI apps similar to how they pay with debit cards. This has led to a race between the banks and fintech apps to give the credit cards that have cashback, points or travel rewards. But not all the cards are alike. Some provide cashback just within their App.
There are some that reward you quickly. Some are excellent only for a user that already has a high usage in one ecosystem, such as Tata or PhonePe. Choosing the UPI credit card from the credit cards list is not necessarily the one with the largest numbers on it; it’s about finding a card that’s right for your spending habits. Read this guide simple and simple to understand all of the Best UPI Credit Card for 2026 and the changes in the rules this year, as well as how to choose the one that best fits your spending needs.
Credit Card on UPI vs ‘Credit Line on UPI’ – They’re Not the Same Thing
Many people mistake the term “credit card on UPI” and “Credit Line on UPI”, however, the two are different. When you get a credit card on UPI, you just connect a credit card (whether it’s physical or virtual, and has its own bill cycle, credit limit and rewards) to a UPI app like Google Pay, PhonePe or Paytm and then use the card to scan and pay at merchants just like you’d swipe it — your monthly credit card bill gets the charge, and it has the same rewards structure as a regular credit card.
A Credit Line on UPI, on the other hand, is a short-term credit facility that is offered directly by a bank via the UPI app, which doesn’t require a full credit card and has a lower credit limit, is approved in a matter of seconds based on your profile and is intended for smaller and more frequent usage of UPI rather than large purchases or building of the rewards.
To sum up: A credit card on UPI is the entire credit card running on UPI and a Credit Line on UPI is a lighter, app-based credit facility, which does not involve a credit card at all.
Best UPI Credit Card in 2026 – Comparison Table
Here’s a quick side-by-side look at the Best UPI Credit Card before we go deeper into each one.
| Card | Issuer | Fee | UPI Cashback | App(s) Supported | Best For |
| Kiwi RuPay Credit Card | Kiwi | Free (paid tier optional) | 1.5% flat, up to 5% with membership | Kiwi app | Everyday scan-and-pay |
| Axis Bank super.money RuPay Card | Axis Bank | Free | 3% via super.money app | super.money app | No-fee cashback |
| Scapia Federal RuPay Card | Federal Bank | Free | 5% on spends above ₹500 | Scapia Pay | Travel rewards |
| Tata Neu Infinity HDFC Card | HDFC Bank | Paid | 1.5% (capped monthly) | Any UPI app | Tata ecosystem shoppers |
| PhonePe HDFC Ultimo Card | HDFC Bank | Paid | 1% Scan & Pay + higher on categories | PhonePe | Heavy PhonePe users |
| HDFC Bank UPI RuPay Card | HDFC Bank | Free (virtual) | Up to 3% on select categories | Any UPI app | Existing HDFC customers |
| Tata Neu Plus HDFC Card | HDFC Bank | Paid | 1% (capped monthly) | Any UPI app | Light Tata shoppers |
| PhonePe HDFC Uno Card | HDFC Bank | Paid | 1% Scan & Pay + select categories | PhonePe | Occasional PhonePe users |
| IDFC FIRST EA₹N Card | IDFC FIRST Bank | Secured (FD-based) | Up to 1% | IDFC FIRST app + others | Students, first-time users |
| SimplySAVE UPI SBI Card | SBI Card | Paid | Reward points, not direct cashback | Any UPI app | SBI loyalists |
10 Best UPI Credit Card in India for 2026
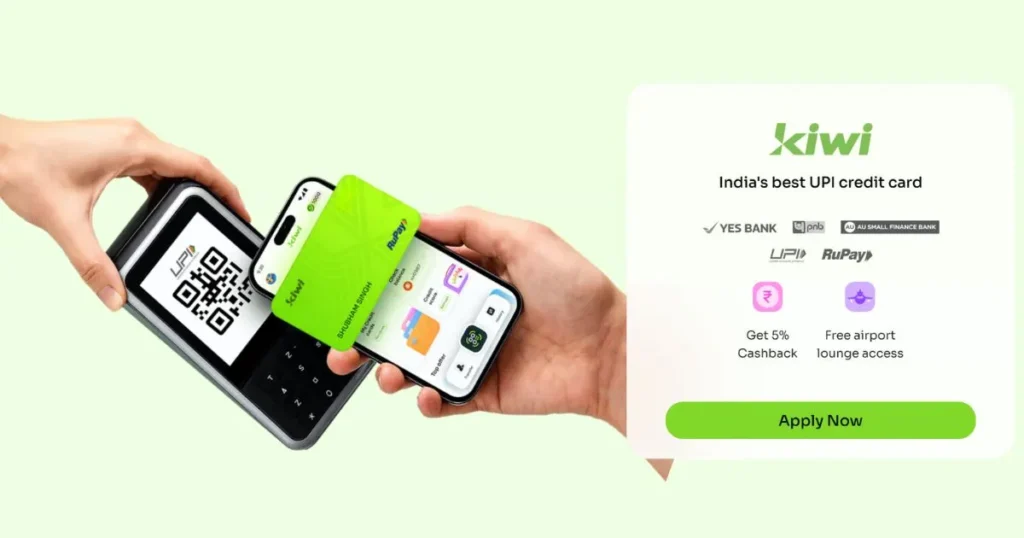
1. Kiwi RuPay Credit Card
Annual Fee: Free to start, with an optional paid membership tier.
UPI Cashback: 1.5% flat, rising up to 5% with the paid Neon plan and spend milestones.
How Cashback Works: Cashback lands straight in your bank account.
Best For: Cashback
Why It’s Good: Simple, direct rewards with no confusing points system.
Kiwi is one of the Best UPI Credit Card for individuals who make a majority of their payments using a Scan-and-Pay at stores, cafes and local vendors as UPI is the very purpose of the card. No points or no coins to convert and then redeem or wait to get, Kiwi pays cashback directly into your bank account – making it much easier to see what you are earning in real time. The free base plan is available for anyone to use without obligation, while the paid Neon membership is only for those who wish to continue, in order to attain higher rewards with spending level achievements.
Key USPs:
- Direct bank cashback
- Free base membership
- UPI-first card design
Pros:
- Easy-to-understand rewards
- No confusing points math
- Lifetime free base plan
Cons:
- Top rate needs paid plan
- Milestones can be tricky
- Best used only for UPI
Link: https://apply.gokiwi.in/
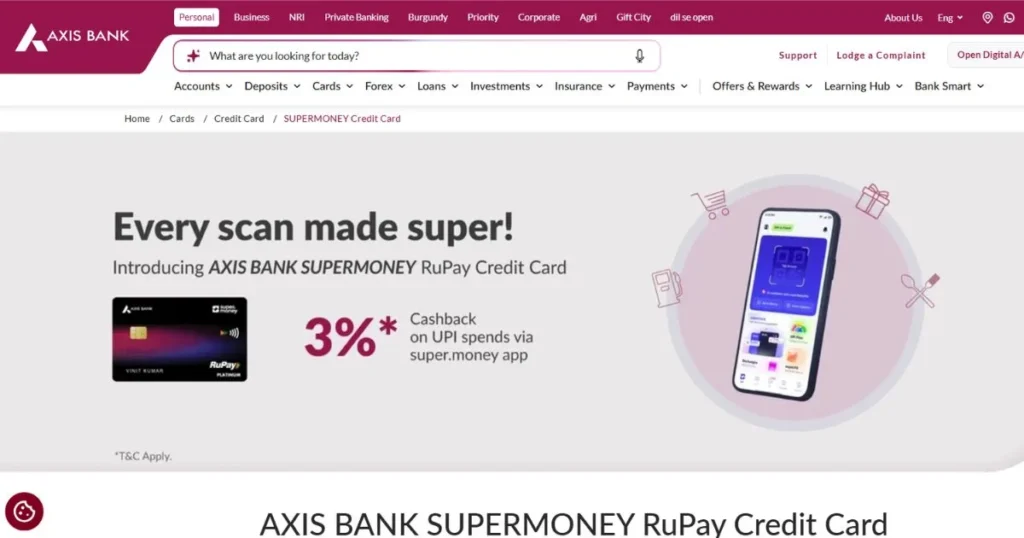
2. Axis Bank Supermoney RuPay Credit Card
Annual Fee: Zero joining and annual fee.
UPI Cashback: 3% inside the super.money app.
How Cashback Works: Cashback is capped at ₹500 per billing cycle.
Best For: Value
Why It’s Good: Strong cashback with absolutely no fee attached.
The Best UPI Credit Card has an outstanding 3% cashback rate on the super.money app — and there’s no joining fee or annual fee. It’s good for those who make moderate or regular UPI payments and not for individuals who make heavy purchases as the ₹500 cashback per cycle limit would soon be reached. Outside of the app, spending will earn just 1% whereas if you use super.money as your primary UPI wallet the actual value will be higher.
Key USPs:
- Zero fee structure
- High 3% reward rate
- Simple app-based tracking
Pros:
- No annual charges ever
- Easy to activate quickly
- Good for regular spends
Cons:
- Monthly cashback cap
- Only 1% outside app
- Some categories excluded
Link: https://www.axis.bank.in/cards/credit-card/supermoney-credit-card
3. Scapia Federal RuPay Credit Card
Annual Fee: No annual fee.
UPI Cashback: 5% as Scapia Coins on spends above ₹500.
How Cashback Works: Coins convert to travel value, not cash.
Best For: Travel
Why It’s Good: Strong reward rate if you already redeem for trips.
Scapia is unique among Best UPI Credit Card because it’s designed for a specific purpose: travel, not even saving money every day. Sounds like a good return rate, but the 5% reward is only applied to purchases exceeding ₹500, meaning that some big spending is required for that to be an attractive reward. This card is not really useful if you’re not someone who uses their reward points to book hotel stays or flights, but rather someone who books such trips to earn cash back into their account.
Key USPs:
- High reward on big spends
- Travel-focused redemption
- No fee card structure
Pros:
- Strong 5% reward rate
- Good for frequent travelers
- No annual fee pressure
Cons:
- Not real cashback
- Needs ₹500+ spends
- Only useful for travel
Link: https://www.federal.bank.in/scapia
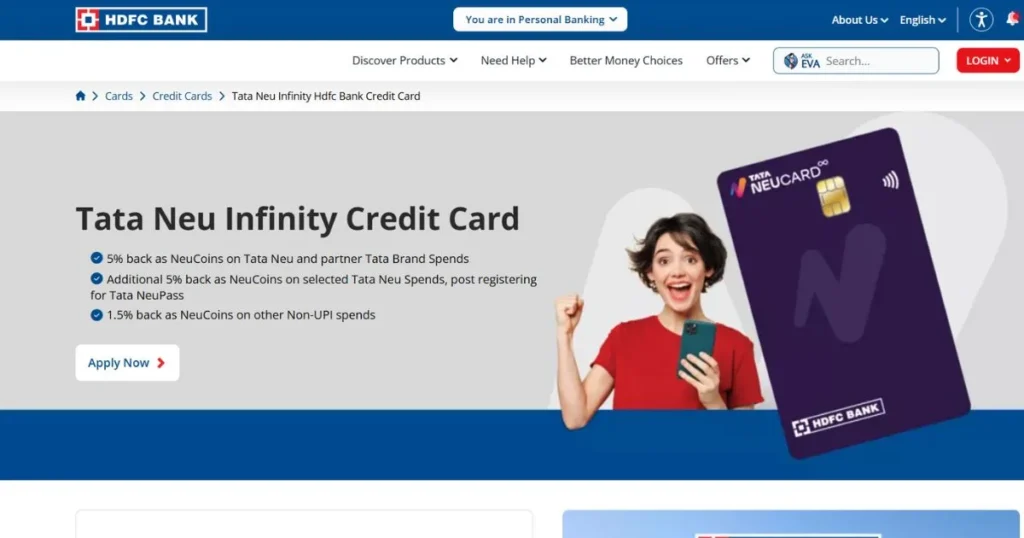
4. Tata Neu Infinity HDFC Bank Credit Card
Annual Fee: Paid annual fee (check current terms).
UPI Cashback: 1.5% back as NeuCoins.
How Cashback Works: Capped at 500 NeuCoins every month.
Best For: Shoppers
Why It’s Good: Big rewards when combined with Tata brand spending.
Tata Neu Infinity is not just in this list of Best UPI Credit Card because of its UPI reward rate, but for the seamless integration it offers with the broader Tata brand. A bit better than average alone, 1.5% spend on UPI is capped at 500 NeuCoins per month. The actual value becomes apparent if you also avail of other offers like buying from Bigbasket, Croma, Tata 1mg and booking an Air India flight, as all these transactions get a higher 5% return. This card provides the same value for customers who are already using Tata brands, and a value that can’t be matched with single-purpose cashback cards.
Key USPs:
- Tata ecosystem rewards
- Premium card benefits
- NeuCoins near ₹1 value
Pros:
- Strong Tata brand rewards
- Good real-world coin value
- Wide partner network
Cons:
- Paid annual fee
- UPI reward capped low
- Best only for Tata users
Link: https://www.hdfc.bank.in/credit-cards/tata-neu-infinity-hdfc-bank-credit-card
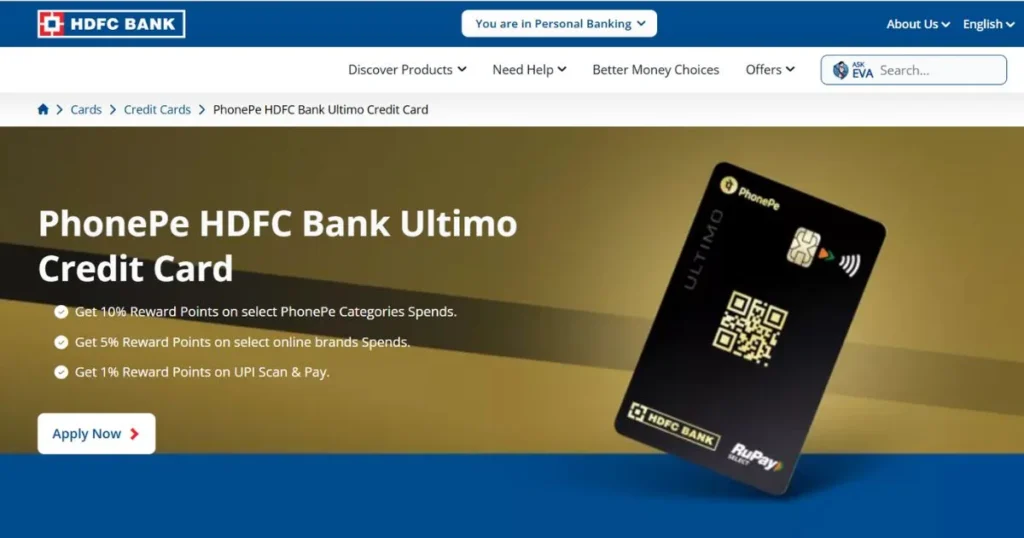
5. PhonePe HDFC Bank Ultimo Credit Card
Annual Fee: Paid annual fee.
UPI Cashback: 1% on Scan & Pay, higher on select categories.
How Cashback Works: Rewards vary sharply by spending category.
Best For: PhonePe
Why It’s Good: Big upside for people who use PhonePe for everything.
Ultimo is the best UPI credit card for PhonePe users who are hardcore users of the app, as it makes the app a complete financial hub. For active users, it’s entirely different with some brands on PhonePe offering up to 10% returns as this is the case with bills, recharges, travel bookings and select online brands, whereas Scan & Pay avails just 1%. To truly make the most of its features, you need to use the card extensively, as the value of its features for making regular payments on the PhonePe app is less experienced if it’s used sparingly.
Key USPs:
- High reward categories
- Deep PhonePe integration
- Multiple earning tiers
Pros:
- Strong non-QR rewards
- Good for bill payments
- Wide category coverage
Cons:
- Low Scan & Pay rate
- Monthly reward caps
- Needs active PhonePe use
Link: https://www.hdfc.bank.in/credit-cards/phonepe-hdfc-bank-ultimo-credit-card
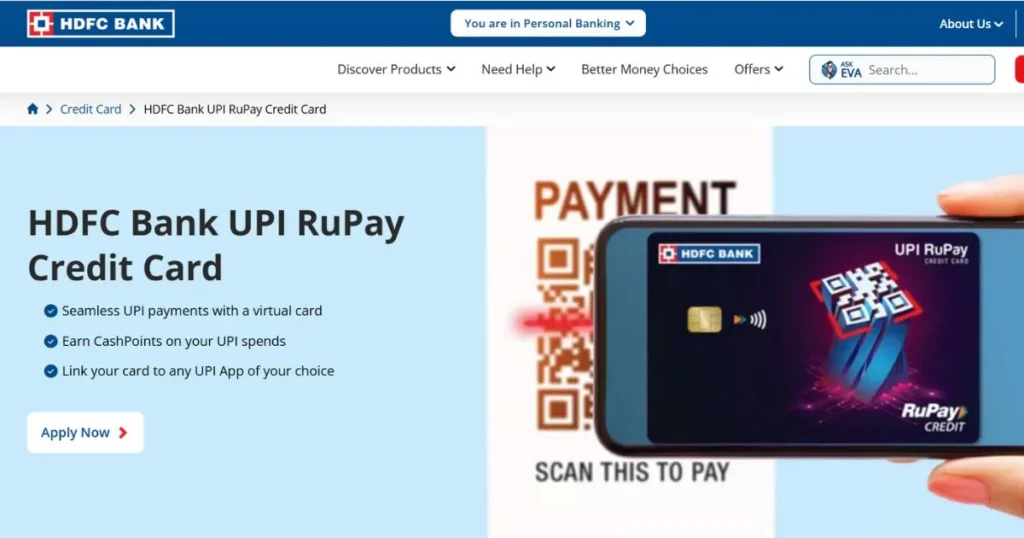
6. HDFC Bank UPI RuPay Credit Card
Annual Fee: No fee, virtual card only.
UPI Cashback: Up to 3% CashPoints on select categories.
How Cashback Works: Rate depends on spend category, not app.
Best For: Simplicity
Why It’s Good: A clean, no-fuss card for existing HDFC customers.
This card is on our list of Best UPI Credit Card because it is not application specific, which means it functions as the same cards regardless of which fintech app you use, be it Google Pay, PhonePe or Paytm. The existing HDFC Bank customers get the best benefits as it is virtual and quick and the CashPoints system is based on the category and encourages them to pay for groceries, dining and utilities, without forcing them to change their payment habits. Though it may not beat the best fintech cashback cards, it’s a reliable go-to option due to its ease of use and versatility.
Key USPs:
- Virtual, instant issuance
- Works with any UPI app
- Category-based rewards
Pros:
- No annual fee
- Easy for HDFC customers
- Flexible app usage
Cons:
- No physical card option
- Category caps apply
- Only for HDFC customers
Link: https://www.hdfc.bank.in/credit-cards/hdfc-bank-upi-rupay-credit-card
7. Tata Neu Plus HDFC Bank Credit Card
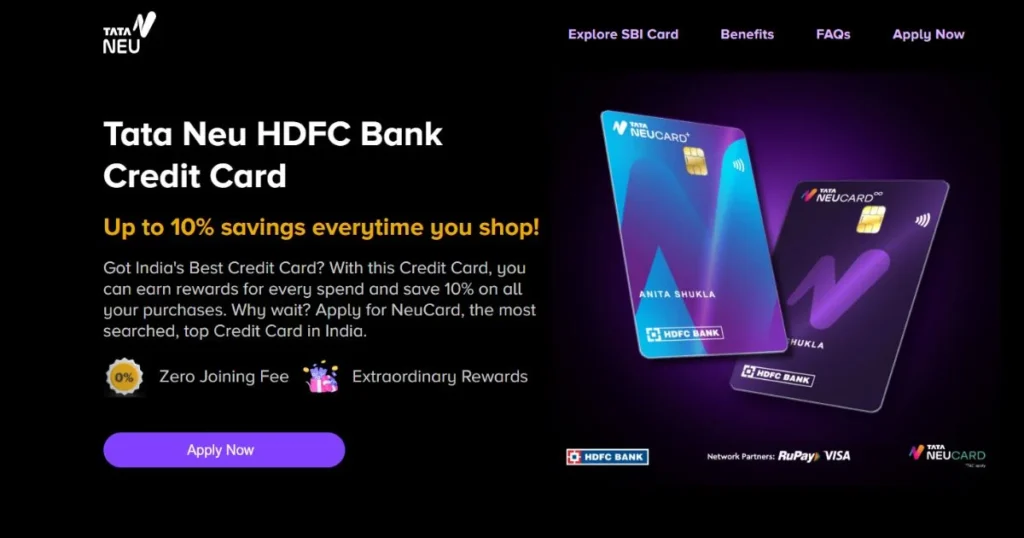
Annual Fee: Paid, but lower than Infinity.
UPI Cashback: 1% back as NeuCoins.
How Cashback Works: Capped at 500 NeuCoins monthly.
Best For: Beginners
Why It’s Good: Entry point into Tata rewards without a big fee.
Neu Plus is a nonchalant brother of Tata Neu Infinity, and it’s certainly one among the Best UPI Credit Card for individuals who enjoy the Tata rewards program however don’t spend that much money to warrant the higher-tier card. Unlike Infinity’s rates, the 1% cashback and 2% on Tata Neu spend is less, but so is the annual fee which makes the cost-to-reward ratio reasonable for the casual Tata shoppers. It’s ideal for someone upgrading to a higher level of card later on and in the meantime – it’s a stepping stone.
Key USPs:
- Lower entry fee
- Tata ecosystem access
- Simple reward structure
Pros:
- Cheaper than Infinity
- Still earns NeuCoins
- Good starter Tata card
Cons:
- Lower reward rate
- Same monthly UPI cap
- Less value outside Tata
Link: https://www.tataneu.com/creditcard/
8. PhonePe HDFC Bank Uno Credit Card
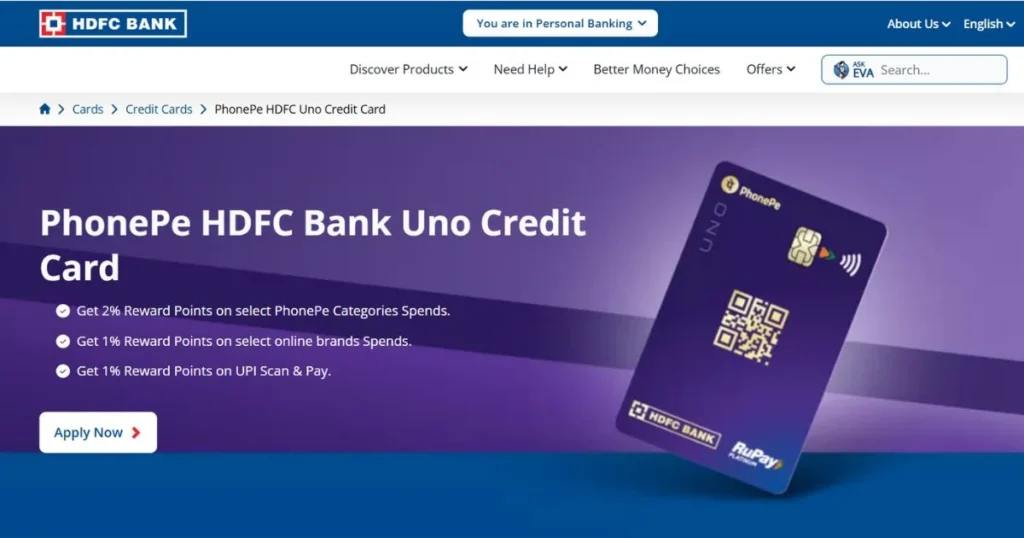
Annual Fee: Paid annual fee, lower tier card.
UPI Cashback: 1% Scan & Pay, plus select category rewards.
How Cashback Works: Smaller reward tiers than Ultimo.
Best For: Casual users
Why It’s Good: Lighter commitment for occasional PhonePe users.
Uno is also in this list of Best UPI Credit Card and is the lighter option than Ultimo, targeted towards the users who use the PhonePe from time to time as they don’t book their every bill using the same app. The rewards are reduced, so are the percentages, and the annual fee is also reduced so that it’s easier to justify for the casual user. It still gives 1% on basic scan & pay transactions which is a good deal for anyone who does not want to adopt a heavier PhonePe lifestyle for some rewards.
Key USPs:
- Lower fee than Ultimo
- Basic PhonePe rewards
- Simple reward tiers
Pros:
- Easier to justify cost
- Steady base rewards
- Good for light users
Cons:
- Smaller reward categories
- Monthly caps apply
- Less value than Ultimo
Link: https://www.hdfc.bank.in/credit-cards/phonepe-hdfc-bank-uno-credit-card
9. IDFC FIRST EA₹N RuPay Credit Card
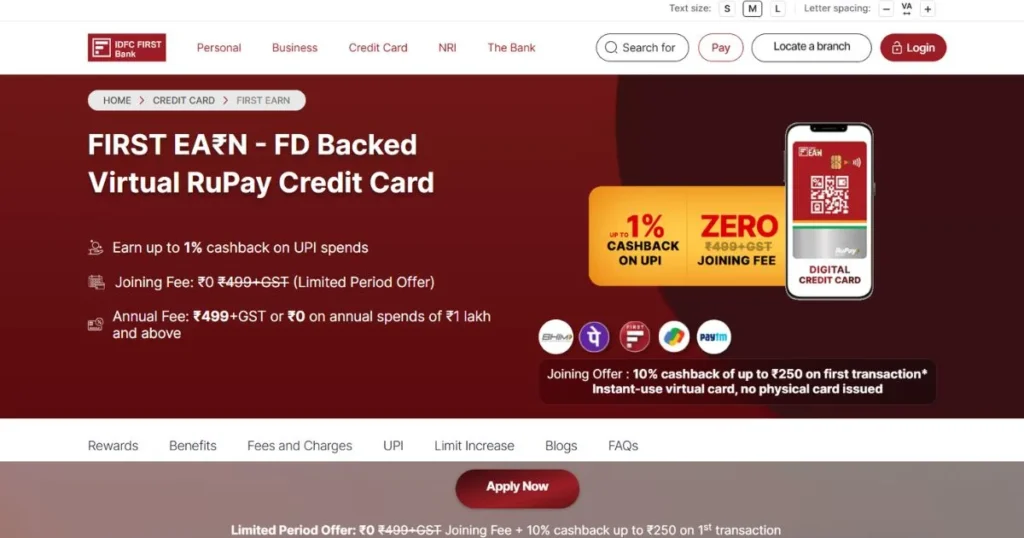
Annual Fee: Secured against a fixed deposit.
UPI Cashback: Up to 1% via the IDFC FIRST app.
How Cashback Works: Lower rate through other UPI apps.
Best For: Beginners
Why It’s Good: A real way to build credit history from scratch.
EA₹N is a Best UPI Credit Card, not because it offers high rewards, but because of its accessibility. Students, new earners and those who do not have any credit history can avail of a proper RuPay credit card as it is issued on a fixed deposit basis.A proper RuPay credit card is usually not possible for students, new earners and people who don’t have any credit history, but this is made possible here by securing it with a fixed deposit. Where the real value lies is that this UPI cashback is a way to begin safely and responsibly establishing a credit score, and the amount is merely 1%, with half of that elsewhere through the IDFC FIRST app.
Key USPs:
- Fixed deposit secured
- Easy approval process
- Builds credit history
Pros:
- Good for beginners
- Low rejection risk
- Builds credit score
Cons:
- Needs fixed deposit
- Lower cashback rate
- Not for high spenders
Link: https://www.idfcfirst.bank.in/credit-card/secured-rupay-credit-card
10. SimplySAVE UPI SBI Card
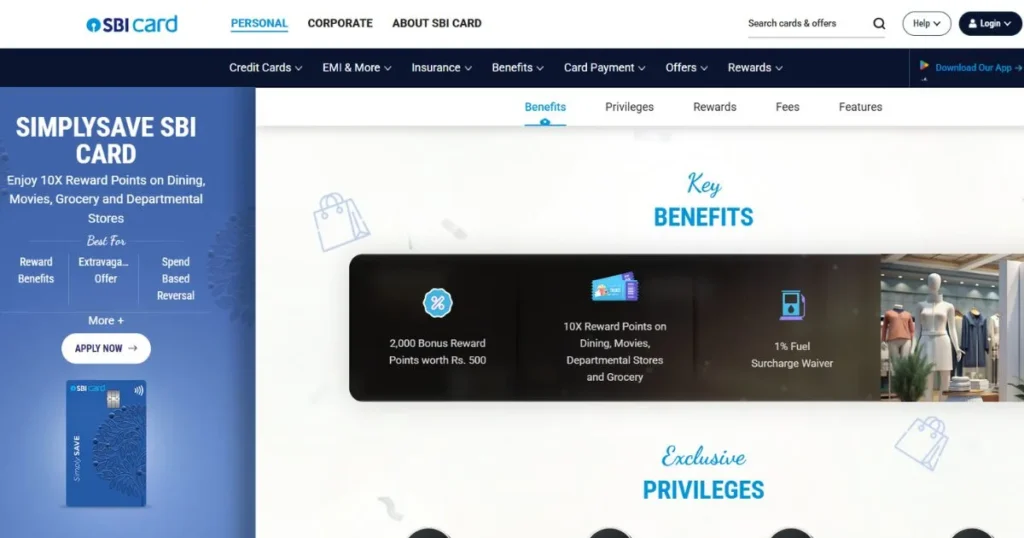
Annual Fee: Paid annual fee.
UPI Cashback: Reward points on select categories.
How Cashback Works: Points earned per ₹150 spent, not direct cashback.
Best For: Traditionalists
Why It’s Good: A trusted issuer with everyday reward categories.
SimplySAVE completes the Best UPI Credit Card list for those who prefer to remain with a trusted traditional bank rather than venture into fintech applications. It doesn’t boast about flashy cashback rates instead it has a more conventional points-based system, where you get 10 points for every ₹150 you spend on dining, movies, grocery and department stores. While there is no lock in because it connects with any UPI application, the worth of the points is generally less than the direct cash back given by cards such as Kiwi or super.money, so it is a comfort choice instead of a maximizer’s choice.
Key USPs:
- Trusted bank issuer
- Works with any UPI app
- Everyday category rewards
Pros:
- Familiar SBI service
- Decent everyday categories
- Works across UPI apps
Cons:
- Points, not cashback
- Lower overall value
- Annual fee applies
Link: https://www.sbicard.com/en/personal/credit-cards/simplysave-sbi-card.html
Best UPI Credit Card by Category
- Best overall: Axis Bank super.money RuPay Card — good cashback, no fees.
- Best life time free: Kiwi RuPay Credit Card — free base plan, direct cash back.
- Best for students: IDFC FIRST EA₹N Card — secure, credit building.
- Best for GPay: HDFC Bank UPI RuPay Card – it works well with any app including Google Pay.
- Best for PhonePe: PhonePe HDFC Ultimo Card — rich in in-app category rewards.
- Kiwi RuPay Credit Card: The best app-based fintech card, built UPI-first from day one.
What Changed for UPI Credit Payments in 2026
- More banks got onboard: This year, many more banks launched RuPay cards with UPI, providing users with much more choice than before.
- Monthly cashback caps reduced: Some cards added or reduced monthly cashback caps to limit cashout costs.
- Restrictions on merchant categories tightened: Additional types of transactions such as lending platforms and account top-ups were denied rewards.
- Fintech apps enhanced rewards: Apps such as Kiwi and super.money offered tiered or milestone-based rewards rather than flat rewards.
How to Set Up a Credit Card (or Credit Line) on UPI
- Open UPI app: Open Google Pay, PhonePe, Paytm, or any other supported app.
- Locate the “Add Credit Card” link: Under payment methods or bank accounts settings.
- Select RuPay Card: Only RuPay credit card can be linked at present.
- Verify with OTP: Check card with OTP sent by bank.
- Use as default (optional): Select to use it as your primary payment method for QR scans.
Is It Safe and Worth It? MDR and Merchant Surcharge Reality Check
- MDR is usually invisible to you: Merchant Discount Rate is a fee charged to the merchant, not directly to you as a customer.
- Certain merchants might pass on costs: A few stores may covertly charge an extra fee for credit card UPI transactions.
- Fees can eat into rewards: If a merchant’s fee is high, your cashback might be better off without using the card there.
- Security is bank-grade: Linking a credit card to UPI is as secure as regular UPI transactions, with the same OTP and encryption protection.
- The golden rule remains the same: Don’t use credit for something you would have paid for anyway.
Conclusion
This is not an easy answer to make as there isn’t a definitive “best” card to pick — the Best UPI Credit Card for 2026 is the one that suits your existing spending habits. If you’re planning to scan a UPI QR code every day, a card that offers cashback is worth considering, such as Kiwi or Axis Bank super money. If you are on the move a lot, Scapia’s coin system may be more advantageous to you.
For Tata brand shoppers and those already utilizing PhonePe, their co-branded cards will surpass any generic choice. Regardless of which card you select from this list of Best UPI Credit Card, keep the golden rule in mind: Don’t spend more than you have to in order to earn rewards, and always pay your bill in full!
FAQs
What is the difference between a UPI credit card and Credit Line on UPI?
A UPI credit card is a normal RuPay credit card connected to a UPI app that can be used for scanning and payments. A Credit Line on UPI is a smaller credit line that is sanctioned directly in the app without a credit card.
Which is better – a RuPay credit card or Credit Line on UPI?
Typically, a RuPay credit card will have a higher reward value and a larger credit limit. A Credit Line on UPI is quick to obtain and more ideal for short-term, sporadic credit usage.
Which is the best UPI credit card in India right now?
Kiwi and Axis Bank super.money credit cards are among the Best UPI Credit Card for direct cashback, while Scapia has the best travel rewards UPI credit cards.
Is there a lifetime-free credit card that works on UPI?
Yes, both Kiwi RuPay Credit Card and HDFC Bank UPI RuPay Card are fee-free at the basic level.
Which credit card is best for Google Pay specifically?
HDFC Bank UPI RuPay Card is a good option as it is not app specific and it works without any hassles on Google Pay and other apps.
What changed with UPI rules in 2026?
There were more banks issuing UPI cards, fewer cashback limits and some merchant categories were restricted to ensure that they are not misused.
Do I get charged extra for UPI credit card payments above Rs 2,000?
There aren’t universal rules for extra charges, however, as they vary by merchant and the card issuer; therefore, it is always important to review the terms of your bank before making any big purchases.
Can students get a UPI-linked credit card or credit line?
Yes, secured options such as IDFC FIRST EA₹N Card allow students to create credit history by securing a student card with a fixed deposit.
Is it safe to link a credit card to UPI apps?
Yes, Linking is also enabled through the same OTP based verification and encryption as all UPI payments making it as secure as UPI payments.
What happens if I miss a UPI credit card or credit line payment?
The consequences of late payments, interest and credit score impact will be identical to if you made a missed payment on a regular credit card or loan.
