Whether it’s the grocery receipt, the airline ticket, the phone bill or the online purchase, you are either getting something back or you are missing out on money. It’s as easy as that; a rewards card is the straightforward choice for 2026, and the selections are bigger than ever. There are some cards that will give you flat cashback on every online purchase. Others convert your money into air miles, hotel points and free trips to the airport lounge. Some are even free for life and are ideal for beginners.
The problem is, the more choices, the more confusion. Two cards may even look very alike, but have completely different annual fees, reward caps, milestone targets and point conversion rules. Choosing the best rewards credit card isn’t about trying to land on the highest numbers and best offers; it’s about finding a card that fits the way you spend.
This guide is designed to do just that. We list 10 popular cards, explain who they’re best for and who should avoid them. Keep reading, identify your spending habits and make informed decisions.
Best Rewards Credit Cards at a Glance
Below is a quick overview of all the cards. The information on fees and offers is from October 2026; always check the most up-to-date terms on the bank’s website when applying.
| Card | Best for | Rewards rate | Annual fee | Intro offer (date) | Regular APR | Credit score needed | Foreign transaction fee |
| HDFC Bank Infinia | Premium travel and high spenders | 5 points per ₹150 (up to 3.3%) | ₹10,000 + taxes (waived on ₹5 lakh spend) | 10,000 reward points on activation (Oct 2026) | 23.88% p.a. | Excellent (750+), invite-only | Low markup (confirm with bank) |
| Axis Bank Magnus | Luxury perks and milestones | 12 EDGE points per ₹200 | ₹12,500 + taxes | 1 free domestic flight ticket (Oct 2026) | 42.58% p.a. | Excellent, high income | Check with bank |
| SBI Cashback | Online shopping | 5% cashback on online spends | ₹999 (waived on ₹2 lakh spend) | ₹5,000 monthly cashback cap (Oct 2026) | 42.00% p.a. | Good to Excellent | Check with bank |
| HDFC Bank Regalia Gold | Balanced travel and lifestyle | 4 points per ₹150 | ₹2,500 (waived on ₹3 lakh spend) | Premium brand vouchers (Oct 2026) | 43.20% p.a. | Good to Excellent | Check with bank |
| Amazon Pay ICICI Bank | Amazon fans, no fee | 5% for Prime members | Zero (lifetime free) | Amazon welcome earnings (Oct 2026) | 42.00% p.a. | Fair to Good | Check with bank |
| Axis Bank Atlas | Frequent flyers | 5 EDGE miles per ₹100 travel spend | ₹5,000 + taxes | 5,000 welcome miles (Oct 2026) | 42.58% p.a. | Excellent | Check with bank |
| American Express Platinum Travel | Milestone travel vouchers | 1 point per ₹50 | ₹5,000 + taxes | 10,000 bonus points (Oct 2026) | 42.00% p.a. | Excellent | Check with bank |
| HDFC Bank Millennia | Young, app-first spenders | 5% on partner digital brands | ₹1,000 (waived on milestone spend) | 1,000 cash points (Oct 2026) | 43.20% p.a. | Good | Check with bank |
| HSBC Visa Platinum | First-time, low-cost card | 2 points per ₹150 | Nil | Free lifestyle subscriptions (Oct 2026) | 39.00% p.a. | Fair to Good | Check with bank |
| Axis Bank Rewards | Everyday shopping and dining | 2 EDGE points per ₹125 | ₹1,000 (waived on milestone spend) | 5,000 EDGE points (Oct 2026) | 42.58% p.a. | Good | Check with bank |
How We Chose These Cards
- Value of the reward: A best rewards credit card must provide actual benefits, so we considered not just the rewards offered but the actual return value on every ₹100 spent.
- Fee vs benefit: If there is a clear benefit, then you are not paying too much. We calculated the break-even point.
- Diverse spenders: Premium travellers, online shoppers, beginners and families.
- Simplicity of redemption: Easy to redeem and easy to understand caps were favored.
- Realistic annual-spend waivers: Fee waivers for cards that offered realistic annual-spend waivers got extra credit.
- Travel and lifestyle benefits: Lounge access, miles transfers, dining deals and insurance were all taken into account.
- Who it’s not suitable for: Like every card, it has its flip side, and we name who should not play it.
- Up-to-date figures: The information was checked for the year 2026 based on public bank information and respected comparison sites.
The 10 Best Rewards Credit Cards in India for 2026
1. HDFC Bank Infinia Credit Card
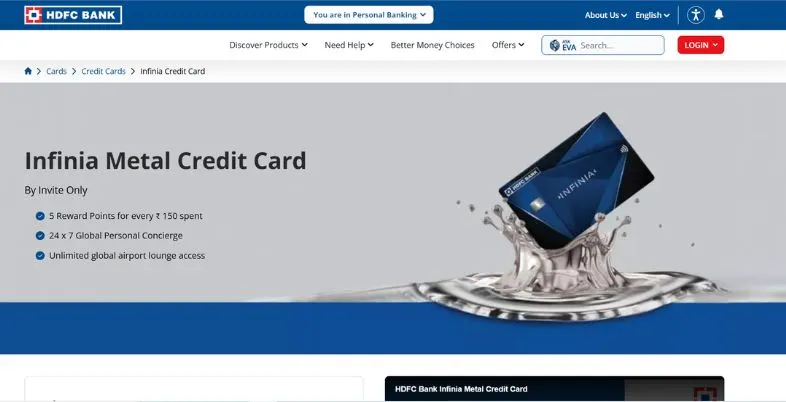
| Profile Key | Card Details |
| Card Name | HDFC Bank Infinia Credit Card |
| Rewards | 5 Reward Points per ₹150 spent (up to 3.3% reward rate) |
| Annual Fee | ₹10,000 + taxes (waived on ₹5 lakh annual spend) |
| Intro Offer (Date) | 10,000 Reward Points upon activation (October 2026) |
| APR | 23.88% per annum |
| Who Should Skip It | Low-volume casual spenders |
| Credit Needed | Excellent (invite-only premium tier) |
| Link | https://www.hdfc.bank.in/credit-cards/infinia-credit-card |
HDFC Bank Infinia is considered the best card in the country and is generally reserved for very high-income earners. The feature that stands out is that its base return rate is as high as 3.3%, with the figure increasing when you book flights and hotels through the bank’s SmartBuy portal.
This card is a real winner in terms of value. Travel is smoother with unlimited domestic and international lounge access and golf privileges, while points can transfer to major airline and hotel partners at a 1:1 ratio. If you are a heavy spender and traveler, the fee becomes very cost-effective very soon.
Pros:
- High reward rate
- Unlimited lounge access
- Low forex markup
- 1:1 mile conversion
- Milestone fee waiver
- Premium golf access
Cons:
- Invite-only access
- High annual fee
- Reward capping rules
- No utility points
- Limited offline redemption
- Strict income criteria
2. Axis Bank Magnus Credit Card
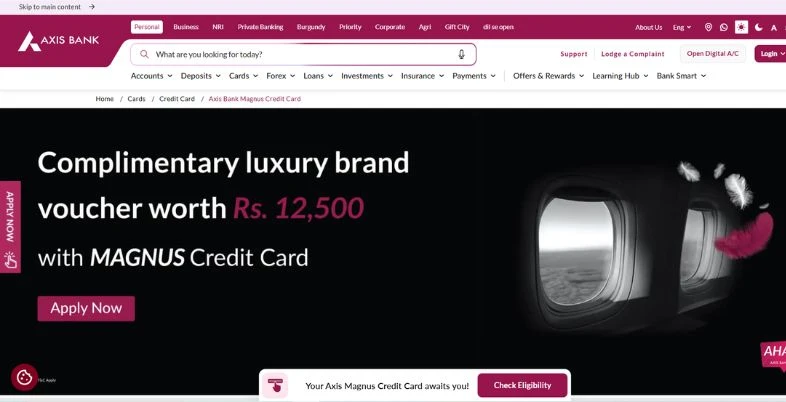
| Profile Key | Card Details |
| Card Name | Axis Bank Magnus Credit Card |
| Rewards | 12 EDGE Reward Points per ₹200 spent |
| Annual Fee | ₹12,500 + taxes |
| Intro Offer (Date) | 1 free domestic flight ticket (October 2026) |
| APR | 42.58% per annum |
| Who Should Skip It | People avoiding high fees |
| Credit Needed | Excellent (high income required) |
| Link | https://www.axis.bank.in/cards/credit-card/axis-bank-magnus-credit-card |
The Axis Bank Magnus is designed for affluent bank customers who seek a luxury lifestyle accompanied with high rewards. What makes it particularly appealing is the milestone system: regular spending leads to significant drops in the total number of bonus points, helping to boost your total return significantly.
Another favourite trick with miles collectors is flexible transfers to international airline partners—Magnus offers these. Everyday value: Airport concierge assistance, entry to the Vip Lounge and special discounts at restaurants and the movies. The downside is the fee, so it’s best if you are going to reach the spending goals.
Pros:
- Strong transfer value
- Big milestone bonuses
- Airport concierge service
- Unlimited lounge entry
- Movie ticket discounts
- Flexible airline partners
Cons:
- Very high fee
- Fewer optimisation options
- High spending milestone
- No fuel points
- Tricky redemption process
- High interest rate
3. SBI Cashback Credit Card
| Profile Key | Card Details |
| Card Name | SBI Cashback Credit Card |
| Rewards | 5% cashback on all online spends |
| Annual Fee | ₹999 (waived on ₹2 lakh annual spend) |
| Intro Offer (Date) | Capped ₹5,000 monthly cashback limit (October 2026) |
| APR | 42.00% per annum |
| Who Should Skip It | Offline retail store shoppers |
| Credit Needed | Good to Excellent |
| Link | https://www.sbicard.com/en/personal/credit-cards/cashback-sbi-card.html |
The SBI Cashback card is tough to beat if you are looking for rewards without any homework. You won’t earn any confusing point tables; you’ll earn a flat 5% back on online spending that’s credited directly to your statement. This may be the best rewards credit card for anyone who shops online, pays bills digitally and orders food or gadgets on the regular.
The advantage of this is obvious: real cash is added to your account without you having to remember it. There is a monthly cap on the amount of cashback earned, but very little cashback is earned offline. When combined with a second card, you’ve got both worlds covered when it comes to in-store purchases.
Pros:
- Flat 5% online cashback
- Automatic statement credit
- Low annual fee
- No point calculations
- Wide online acceptance
- Easy fee waiver
Cons:
- Monthly cashback cap
- Poor offline rewards
- No lounge access
- No luxury perks
- Few utility rewards
- Limited festive deals
4. HDFC Bank Regalia Gold Credit Card
| Profile Key | Card Details |
| Card Name | HDFC Bank Regalia Gold Credit Card |
| Rewards | 4 Reward Points per ₹150 spent |
| Annual Fee | ₹2,500 (waived on ₹3 lakh annual spend) |
| Intro Offer (Date) | Complimentary premium brand vouchers (October 2026) |
| APR | 43.20% per annum |
| Who Should Skip It | People wanting direct cashback |
| Credit Needed | Good to Excellent |
| Link | https://www.hdfc.bank.in/credit-cards/regalia-gold-credit-card |
The Regalia Gold combines travel benefits and normal lifestyle with benefits and is a good choice for working people. Accumulated points are available for apparel and airline purchases, and annual thresholds award premium brand vouchers in secret to boost the total return.
The balance is what makes it special. Reasonable spending targets go hand in hand with complimentary lounge access, travel insurance cover, and priority customer support. It will be more than what the premium level offers, but not quite as expensive, and for those who travel a couple of times a year, it has a broad and useful combination of advantages.
Pros:
- Boosted retail rewards
- Free lounge access
- Reachable milestones
- Wide redemption catalogue
- High flight value
- Priority support
Cons:
- Notable annual fee
- Points expiry tracking
- Clunky booking engine
- Limited fuel waivers
- Low base value
- Monthly capping rules
5. Amazon Pay ICICI Bank Credit Card
| Profile Key | Card Details |
| Card Name | Amazon Pay ICICI Bank Credit Card |
| Rewards | 5% unlimited cashback for Prime members |
| Annual Fee | Zero (lifetime free card) |
| Intro Offer (Date) | Free Amazon welcome earnings (October 2026) |
| APR | 42.00% per annum |
| Who Should Skip It | Non-Amazon ecosystem users |
| Credit Needed | Fair to Good |
| Link | https://www.icicibank.com |
This co-branded card is a popular one since it does not involve any cost for the owner. No joining fees or annual fees, and Prime members will get an unlimited 5% back on Amazon shopping. This is a monthly savings that works out automatically for a family that already purchases most items from the platform.
The simplicity is the growth benefit: rewards are rewards that come in the form of an Amazon Pay balance that you can use towards thousands of partner merchants, with no expiration date. There are no perks, including lounge access and very minimal returns outside of Amazon, so use it as a shopping partner and not as a single card.
Pros:
- Lifetime free
- Unlimited 5% rewards
- Rewards never expire
- Automatic wallet credit
- Easy app management
- Simple welcome bonus
Cons:
- Needs Prime membership
- Rewards stay in wallet
- No lounge access
- Weak offline earnings
- No milestone gifts
- Limited dining deals
6. Axis Bank Atlas Credit Card
| Profile Key | Card Details |
| Card Name | Axis Bank Atlas Credit Card |
| Rewards | 5 EDGE Miles per ₹100 travel spend |
| Annual Fee | ₹5,000 + taxes |
| Intro Offer (Date) | 5,000 welcome travel miles (October 2026) |
| APR | 42.58% per annum |
| Who Should Skip It | Infrequent non-traveling individuals |
| Credit Needed | Excellent |
| Link | https://www.axis.bank.in/cards/credit-card/axis-bank-atlas-credit-card |
The Axis Atlas is for the mind of a mileage man, not a rupee man. It offers good mileage on flights and hotel stays and will reward you the more you spend on travel over the course of the year. For frequent flyers, it ranks among the best rewards credit card options available for turning trips into free trips.
It is special regarding the flexible transfer program, which permits travelers to move from different airline and hotel partners without being bound to any specific carrier. Lounge visits and direct booking bonuses bring additional value. For those who don’t travel often, however, returns on shopping are not that strong, and the cost of the fee is not worth it.
Pros:
- Fast mile earning
- Multi-airline transfers
- Tier upgrade perks
- Generous welcome miles
- Lounge access included
- Direct booking bonuses
Cons:
- High annual fee
- Poor shopping returns
- Complex tier rules
- No local cashbacks
- Strict document checks
- Limited dining perks
7. American Express Platinum Travel Credit Card
| Profile Key | Card Details |
| Card Name | American Express Platinum Travel Credit Card |
| Rewards | 1 Membership Rewards point per ₹50 spent |
| Annual Fee | ₹5,000 + taxes |
| Intro Offer (Date) | 10,000 bonus activation points (October 2026) |
| APR | 42.00% per annum |
| Who Should Skip It | Low-spending tier individuals |
| Credit Needed | Excellent |
| Link | https://www.americanexpress.com |
This Amex Platinum Travel card is well known for its milestone design. Achieve your annual spending goals and earn valuable travel vouchers and hotel discounts. It’s ideal for customers living a premium lifestyle who use the majority of their home finances on one card to achieve them.
Its true strength is the American Express service experience, with prompt customer service and robust purchase and fraud protection. The base earning rate is relatively low, and the value is primarily from milestones. Use it as a bonus card for disciplined, high-spending, and not as a “regular” card.
Pros:
- Big travel vouchers
- Luxury hotel perks
- Excellent customer care
- Great dining rewards
- Companion benefits
- Strong purchase protection
Cons:
- High annual fee
- Lower merchant acceptance
- Low base rewards
- No fuel benefits
- Strict credit review
- High cash withdrawal fees
8. HDFC Bank Millennia Credit Card
| Profile Key | Card Details |
| Card Name | HDFC Bank Millennia Credit Card |
| Rewards | 5% cashback on partner digital brands |
| Annual Fee | ₹1,000 (waived on milestone spend) |
| Intro Offer (Date) | 1,000 cash point welcome credit (October 2026) |
| APR | 43.20% per annum |
| Who Should Skip It | Wholesale physical bulk buyers |
| Credit Needed | Good |
| Link | https://www.hdfc.bank.in/credit-cards/millennia-credit-card |
Millennia offers cashback to 5% of its young, app-first customers and rewards them for using some of the popular apps it has partnered with, including food delivery, streaming and ride-hailing. If you’re spending a lot of your money on your phone, then you won’t even realize it’s saving you money every day.
To make it easy, cash points can be redeemed straight off your statement. It also comes with an uncommon amenity in this class: access to domestic airports’ lounges at a very affordable rate. Be mindful of the monthly limits and the low rewards on offline and overseas purchases before you invest.
Pros:
- 5% digital cashback
- Statement redemption
- Domestic lounge access
- Affordable annual cost
- Quarterly milestone bonuses
- Good merchant discounts
Cons:
- Monthly reward caps
- Low offline earnings
- No wallet-load points
- Limited international perks
- Surcharge waiver caps
- Complex categories
9. HSBC Visa Platinum Credit Card
| Profile Key | Card Details |
| Card Name | HSBC Visa Platinum Credit Card |
| Rewards | 2 Reward Points per ₹150 spent |
| Annual Fee | Nil (no conditional charges) |
| Intro Offer (Date) | Free premium lifestyle subscriptions (October 2026) |
| APR | 39.00% per annum |
| Who Should Skip It | High-spending premium mile seekers |
| Credit Needed | Fair to Good |
| Link | https://www.hsbc.bank.in/credit-cards/products/visa-platinum/? |
The HSBC Visa Platinum is a soft-spot rewards card. It doesn’t have an annual fee and doesn’t impose any conditions, so it allows you to build a credit history without having to pay anything extra. It can be the best rewards credit card to get you started for students, first-jobbers and those who don’t like risky spending, as you have nothing to lose.
The card also has higher 5X rewards after meeting certain spend thresholds annually, along with entertainment packages, movie deals and dining deals designed for young urban professionals. The base earning rate is not high, and there is no lounge benefit, so many users upgrade to a more capable card later.
Pros:
- Zero annual fee
- 5X bonus points
- Free streaming bundles
- Restaurant discounts
- Lower interest rate
- Easy digital onboarding
Cons:
- Low base rewards
- No lounge perks
- Weak milestone vouchers
- Limited transfer value
- Small merchant network
- No concierge support
10. Axis Bank Rewards Credit Card
| Profile Key | Card Details |
| Card Name | Axis Bank Rewards Credit Card |
| Rewards | 2 EDGE Reward Points per ₹125 spent |
| Annual Fee | ₹1,000 (waived on milestone spend) |
| Intro Offer (Date) | 5,000 EDGE activation points (October 2026) |
| APR | 42.58% per annum |
| Who Should Skip It | Exclusive international business travelers |
| Credit Needed | Good |
| Link | https://www.axis.bank.in/cards/credit-card/rewards-credit-card |
The Axis Rewards card is usable for all-day shopping and family dinners. It features a major reward of 10X from select online partner merchants, helping normal purchases earn more than the base rate. There are also monthly spending bonuses which are used to add extra loyalty points periodically.
It is excellent at offering an easy and flexible reward system and quarterly domestic lounge benefits at a low price. Not designed for travel abroad for business, the waiver requires a decent amount of yearly spending. It’s a good option for the average family looking for a well-rounded, hassle-free card.
Pros:
- 10X shopping rewards
- High welcome points
- Monthly spending bonuses
- Domestic lounge access
- Flexible redemption
- City dining discounts
Cons:
- Noticeable base fee
- No fuel rewards
- Capped multipliers
- Low international value
- Slow point credit
- High waiver threshold
Cash Back vs Points vs Miles: Which Type Is Right for You?
Before you opt for one of the best rewards credit cards, you need to decide which currency you wish to be rewarded in. There are different strengths in each type.
| Feature | Cash back | Reward points | Travel miles |
| How it works | A percentage of spend returns as money | Points earned per ₹ spent, redeemed for products, vouchers or statement credit | Miles earned mainly on travel, transferred to airline or hotel partners |
| Best for | Beginners and online shoppers | Regular spenders who like variety | Frequent flyers and holiday planners |
| Value clarity | Very clear, 1 rupee equals 1 rupee | Varies by how you redeem | Can be highest, but depends on the route |
| Effort needed | Almost none | Moderate | High, needs planning |
| Risk of waste | Low | Medium, points may expire or lose value | Medium, award seats can be scarce |
| Example cards | SBI Cashback, Amazon Pay ICICI | HDFC Regalia Gold, Axis Rewards | Axis Atlas, HDFC Infinia |
How to Pick the Best Rewards Credit Card for Your Spending
- Monitor the previous 3 months of expenditures: Record how much money is spent on groceries, gas, online shopping, eating out, bills and traveling.
- Identify your largest category: Take a card that pays the most on the top category of your spending.
- Calculate annual rewards: Monthly spend x reward rate minus annual fee.
- Know the waiver target: For some households, it may be easy to pay ₹2 lakh, and for others, it may not be possible.
- Pay attention to the caps: A 5% rate with a low monthly cap is not as thrilling as a high monthly cap.
- Acknowledge the privileges you will enjoy: If you fly just once a year, the lounge access is of no value.
- Fit the credit profile: Only use cards that fit within your credit profile range to prevent unnecessary rejection.
- Consider two cards: One online cashback card, plus one all-rounder is sometimes better than one card.
Do Rewards Beat Interest? Why Paying in Full Matters
- Interest is greater than rewards: The best rewards credit card will never out-compete debt. APRs in the range of approximately 40% per year can cost you several years of rewards in just a month’s time.
- Example: If you earn ₹1,000 in rewards and pay ₹2,000 in interest, you’re left with ₹1,000.
- Pay the full statement balance: This will maintain the interest-free period for new purchases.
- Don’t pay the minimum: This will leave debt in place, and the interest will continue to mount.
- Set auto-pay: When you set up an automatic payment for the full amount, you won’t forget.
- Never pay more for points: If it wasn’t going to be purchased anyway, it is not a gain.
- Lower interest is more important than rewards for balance carriers: When you carry a balance often, lower interest rates are more important.
Conclusion
The right card is the one that fits your life, not the one with the loudest advertisement. Premium travellers will enjoy the HDFC Infinia, Axis Magnus or Axis Atlas. The SBI Cashback, Amazon Pay ICICI and HDFC Millennia are some of the best ways for online shoppers to save huge amounts. The HSBC Visa Platinum is a good choice for beginners, and families might prefer the more well-rounded Regalia Gold or Axis Rewards.
Of course, no matter which one you choose, there’s a simple rule to follow: Pay the bill in full and on time each month; interest will wash away rewards quicker than anything. Review your spending habits, read the fine print and select the best rewards credit card that will save you money in 2026.
Also Read:
FAQs
What is the best rewards credit card in general?
There is no winner, just a number of winners. HDFC Infinia offers the best reward, SBI Cashback is the most convenient online savings, and Amazon Pay ICICI is a free card. The best fit is determined by your spending habits.
Which is better, a cash back card or travel card?
Cash back is better if you want simple, guaranteed savings. A travel card is more advantageous if you are a frequent flyer and will be using miles and transfers, plus lounges. If you can afford to spend less than ₹5,00,000 per year? Typically, cash back is the winner.
Are rewards credit cards worth it if I carry a balance?
Usually not. Interest rates run at about 40%, which is much higher than rewards of 1% to 5%. Pay entirely or opt for a card with low interest rates.
What is a good credit score for a rewards card?
FICO scores of between 650 and 700 may be good enough for entry-level cards. The mid-range cards like 700 or higher, and the premium cards like 750 or higher, and higher income.
How many cards should I make for rewards?
For most people, two or three cards is all they need, one for online cashback, one for their daily spending and, if they travel, one travel card. Only have as many as you can afford and pay off on time.
Are rewards points valid for a specific period of time?
This is subject to the card. Certain programmes have time limits for their points, others, such as Amazon Pay balances, don’t. Read the terms and conditions of your card, and use it in time.
